Ontario’s Mortgage-Arrears Warning Needs a Household-Stress Ledger
CMHC is not calling a national mortgage crisis. It is warning that pressure is concentrating in Ontario first — and Ottawa should be forced to publish the household receipts before arrears become defaults.
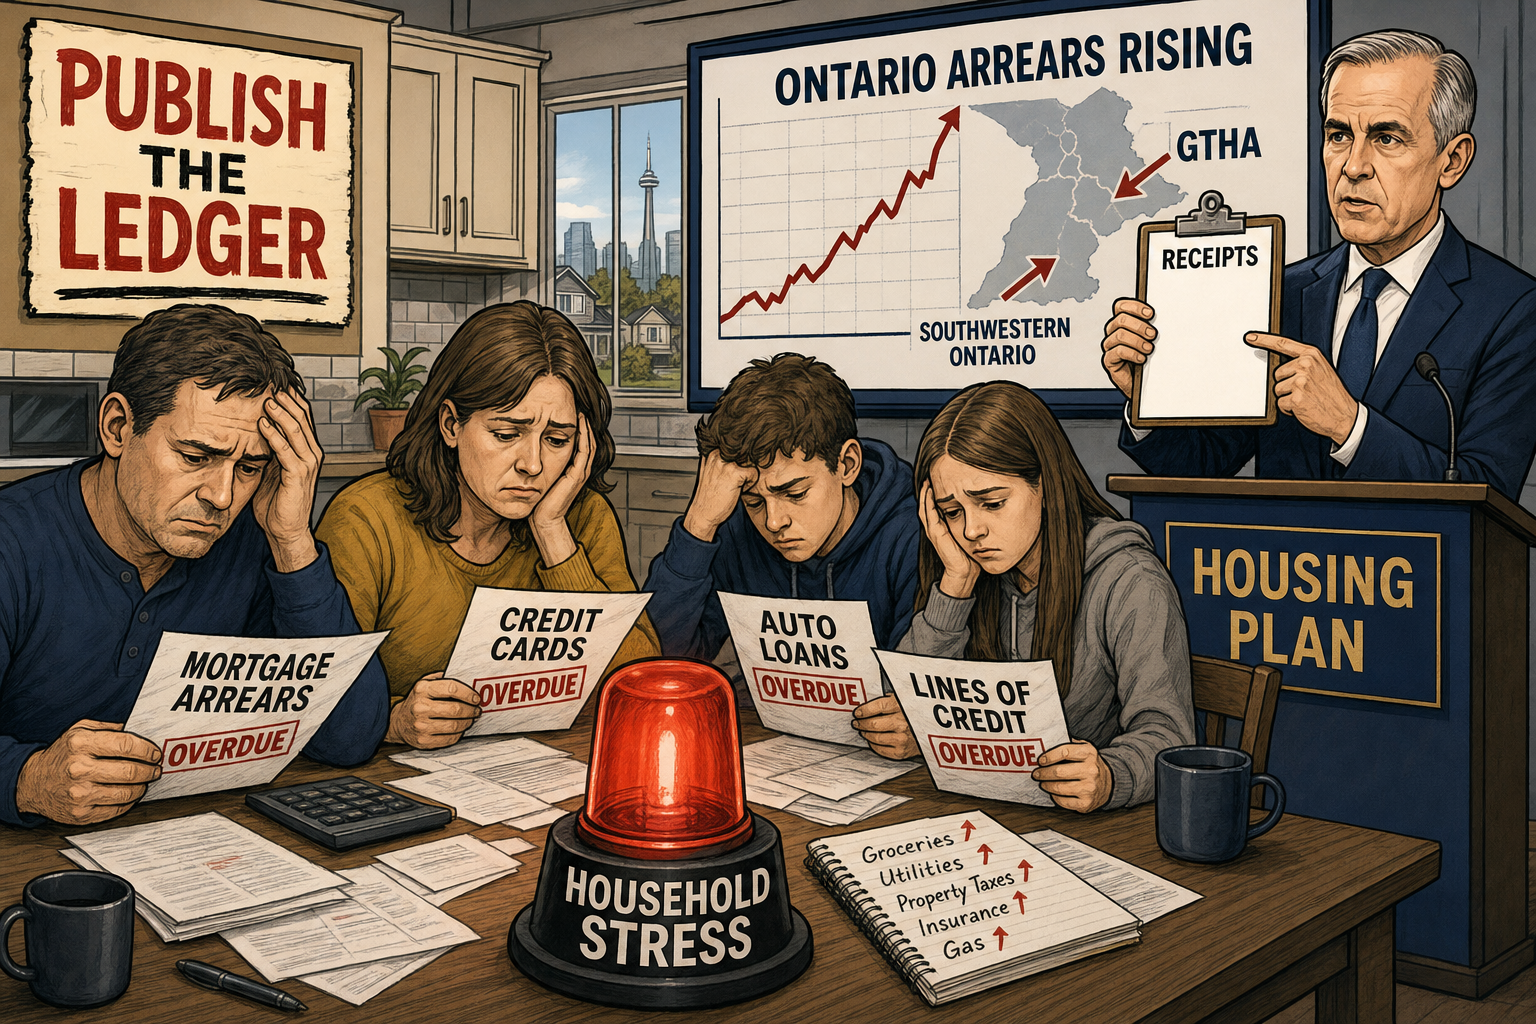
Canada Mortgage and Housing Corporation’s latest warning should cut through the government’s usual housing spin. CMHC says Ontario’s mortgage arrears rate reached 0.32% in the second quarter of 2026 and is expected to keep rising through mid-2027. That is not a collapse. It is an early-warning light, and responsible governments do not wait until the dashboard is flashing red before admitting families are under pressure.
The geography matters. CMHC says Ontario is projected to see the largest and most sustained increase in mortgage arrears, concentrated in the Greater Toronto and Hamilton Area and Southwestern Ontario. It also links that pressure to trade tensions affecting manufacturing sectors, including autos, plus labour-market uncertainty and softer housing conditions. In plain English: the same households hit by high prices, renewal stress and job risk are now showing up in the arrears data.
That should make Prime Minister Mark Carney’s housing-and-trade agenda answerable to a much more basic test: are federal promises reducing household stress, or just generating announcements? Ottawa has spent years talking about affordability, supply, industrial strategy and worker support. But CMHC’s warning points to the household balance sheet, not the podium. If a family is juggling a mortgage, a credit card, an auto loan and a line of credit, a ribbon-cutting does not pay the bill.
CMHC’s release is careful. It says mortgage stress is not widespread across Canada. It notes that arrears have declined in Alberta and Saskatchewan and are expected to remain stable through mid-2027, while British Columbia and Atlantic Canada are expected to see a more moderate rise. That makes the accountability question sharper, not softer. If the problem is regional and tied to identifiable labour-market risks, then the response should be targeted, measurable and public.
The federal government should publish a household-stress ledger for Ontario: mortgage arrears by region, renewal-risk exposure, non-mortgage delinquency trends, auto-sector job-risk indicators, insolvency signals, federal housing dollars by project and the number of homes actually completed. Add the trade file too: tariff exposure, manufacturing layoffs, worker-support spending, and what relief has actually reached affected households.
None of this requires speculation. It requires receipts. If Ottawa’s housing programs are working, the ledger will show it. If trade tensions are pushing parts of Ontario toward deeper household stress, Canadians deserve to know that before the damage spreads. And if the government’s answer is more slogans about building, competing and protecting workers, then it should be asked the only question that matters: where is the household balance-sheet proof?
- CNW / CMHC: Ontario mortgage arrears expected to rise through mid-2027
- Canada Mortgage and Housing Corporation: Residential Mortgage Industry Report, Fall 2026
- iVoteLiberal.com: Housing Catastrophe background and duplicate check
This article argues for greater public disclosure of household-stress indicators. It does not claim CMHC has found a broad national mortgage crisis.