The Disability Tax-Credit Clawback Ledger
The Liberal tax-cut headline now has a top-up patch. Canadians still deserve the disability-credit impact table before 2026 returns are filed.
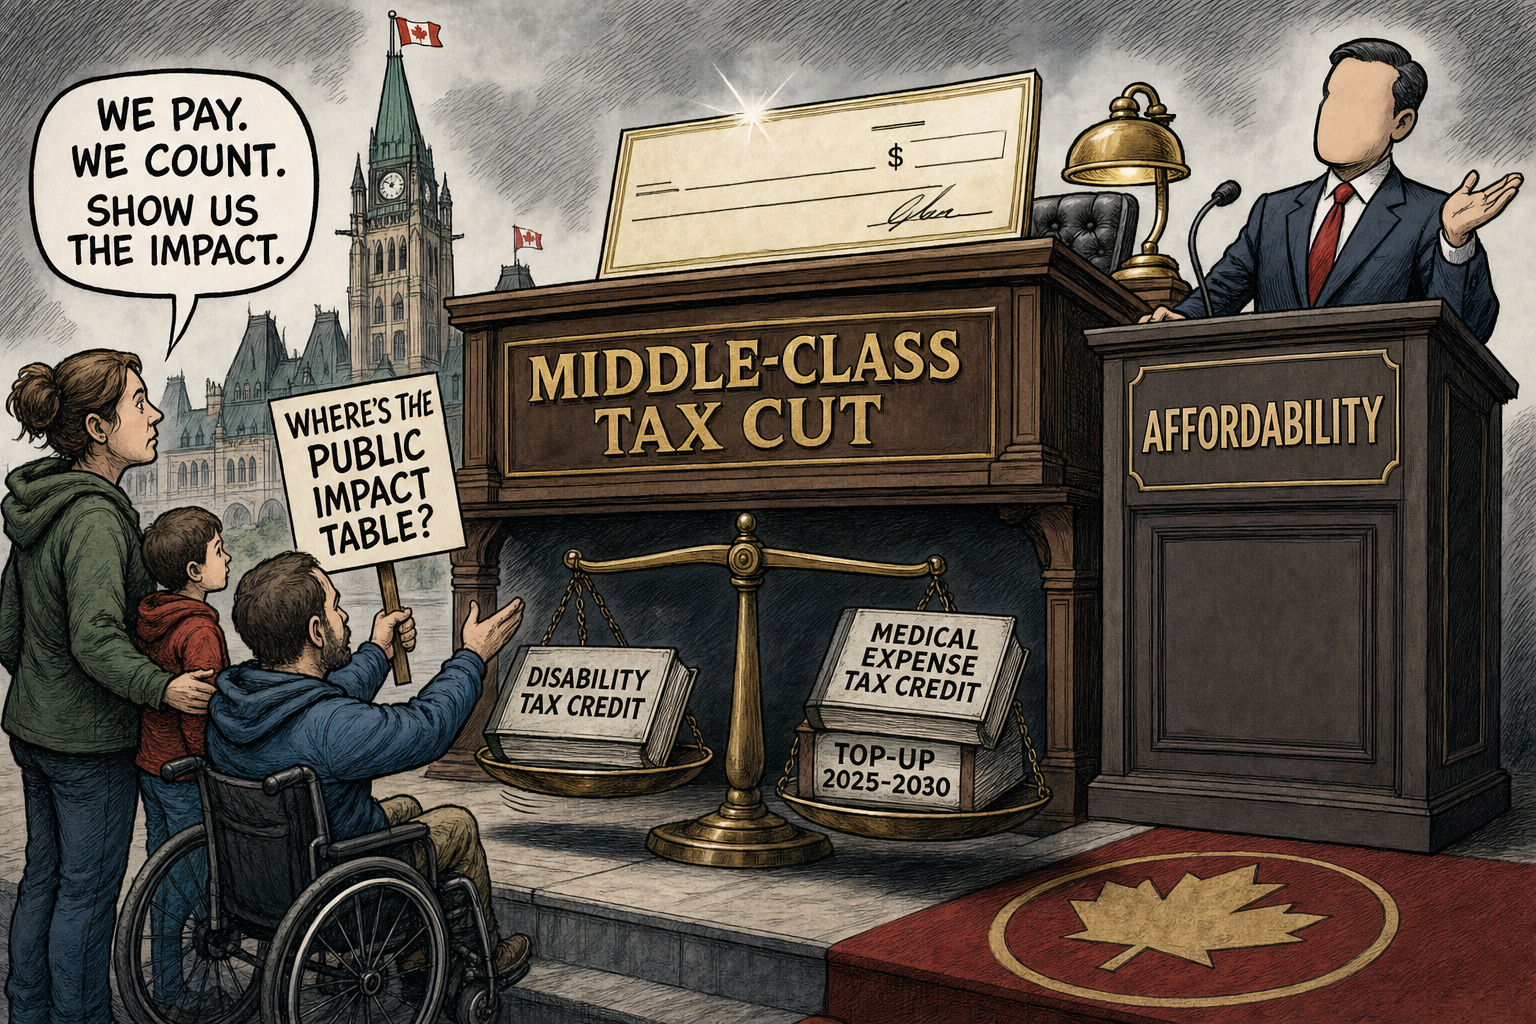
The Liberal sales pitch was clean: Bill C-4 would cut the lowest federal tax rate and save two-income families up to $840 in 2026. The fine print was not so clean. Because many non-refundable tax credits are calculated using that same lowest rate, the value of the Disability Tax Credit and Medical Expense Tax Credit was also pushed down.
This is not a partisan theory. The Parliamentary Budget Officer estimated that the rate cut, as proposed, would adversely affect 19,690 single filers and 19,420 couples in 2026, raising federal tax payable by $141 and $155 on average. Among affected filers not subject to Alternative Minimum Tax, PBO said 17 per cent of single filers and 35 per cent of couples claimed the disability amount.
Disability advocates spotted the problem before the bill became law. Canadian Press reported in June 2025 that Inclusion Canada supported the lower tax rate in principle but warned the formula would shrink disability-related credits. March of Dimes told the House finance committee the DTC value would drop by about $101 per claimant in 2026, and its pre-budget submission urged Ottawa to preserve the 15 per cent calculation for the DTC and METC.
Ottawa’s answer came later. Bill C-4 received Royal Assent on March 12, 2026. Finance Canada’s June 2026 report says Bill C-15 then created a temporary Top-Up Tax Credit for 2025 through 2030, intended to ensure no one’s tax liability increases where credits and income exceed the first bracket threshold. That patch matters. It also proves the original affordability headline needed a repair crew.
Finance’s own report still shows the broader ledger: applying 14 per cent instead of 15 per cent is projected to reduce the value of non-refundable tax relief by about $5.42 billion in 2026, including $86 million tied to disability amounts and $167 million tied to medical expenses. The government says tax savings outweigh the credit reduction for nearly all taxpayers. Fine. Then publish the taxpayer-facing receipts.
Before Canadians file 2026 returns, cabinet should release the disability-credit impact table by income, province, family status, age, DTC transfer status, child supplement status and medical-expense claims. CRA should also disclose how affected taxpayers will see the top-up on their assessments, whether it is automatic, how errors can be appealed, and what happens after 2030.
Conservatives should be precise here: a broad tax cut can still be good policy. But affordability politics becomes cynical when the government advertises the cheque and hides the offsets. Disabled Canadians should not have to rely on committee testimony, watchdog math and advocacy groups to discover what changed inside their tax return.
- Parliamentary Budget Officer: Individuals adversely affected by the Middle-Class Tax Cut
- Department of Finance Canada: Legislation to make life more affordable receives Royal Assent
- Department of Finance Canada: Report on the Impact of Reducing the Lowest Marginal Personal Income Tax Rate on Non-Refundable Tax Credits
- Canadian Press via 980 CJME: People with disabilities concerned proposed Liberal bill will increase federal taxes
- House of Commons Standing Committee on Finance: Evidence No. 6, 45th Parliament, 1st Session
- March of Dimes Canada: Federal Pre-Budget Submission 2026-27
This article recognizes that Finance Canada says the temporary top-up is intended to prevent increased tax liability in affected cases. The accountability question is whether taxpayers can see and verify the disability-credit impact and the top-up calculation.